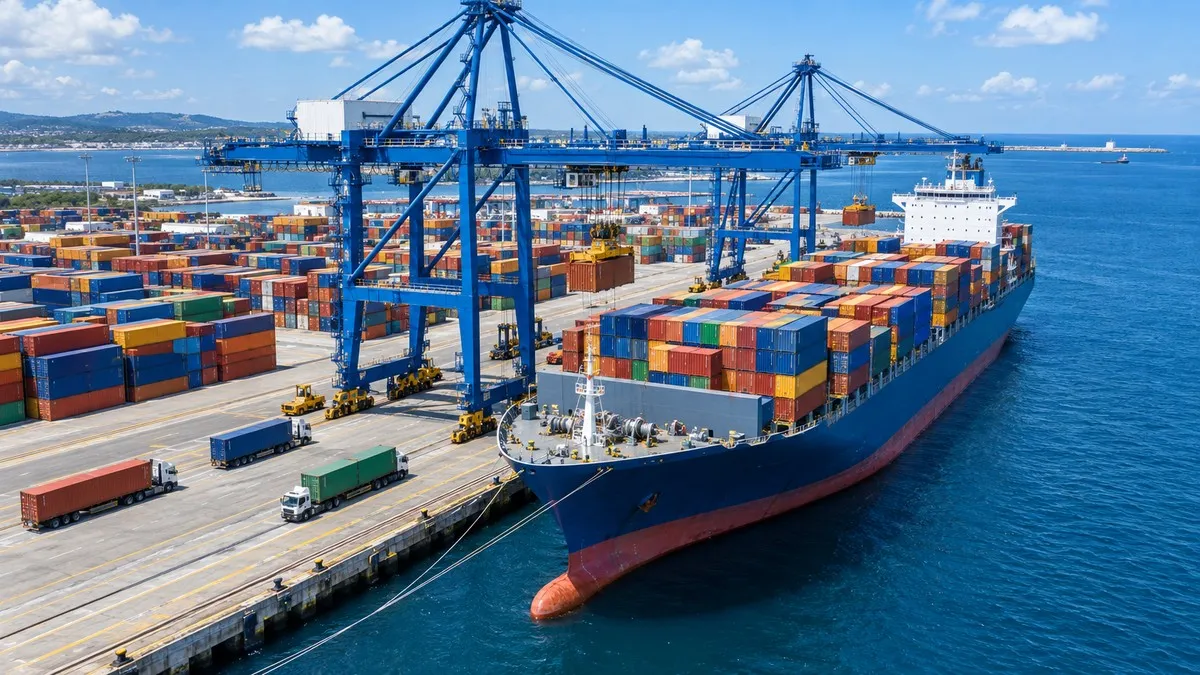
A letter of credit is a bank's written promise to pay a seller a fixed amount, on condition that the seller presents documents that match the terms of the credit. The buyer's bank carries the payment risk, so the exporter is paid without having to trust the importer, and the importer pays only once the papers show the goods were shipped as agreed.
That promise holds only if every stage runs on time and every document lines up. This guide follows the full process, from the sales contract to the moment the money moves, with the deadlines the international rules set and the mistakes that stall most payments.
What a Letter of Credit Is and Who Takes Part
Banks also call a letter of credit a documentary credit, because payment depends on documents, not on the goods themselves. The bank never inspects the cargo. It checks a stack of paper: the commercial invoice, the bill of lading, the insurance certificate and whatever else the credit lists.
Most credits are issued subject to the UCP 600 rules, published by the International Chamber of Commerce. The first version appeared in 1933, and UCP 600 is the sixth. Under these rules a credit is irrevocable by definition: any arrangement, whatever it is called, that commits the issuing bank to pay against a complying presentation.
The parties in a documentary credit
Five roles appear in almost every transaction, and the rules define each one:
- Applicant: the buyer, who asks its bank to issue the credit.
- Beneficiary: the seller, who is paid under it.
- Issuing bank: the buyer's bank, which makes the payment promise.
- Advising bank: a bank in the seller's country that passes the credit on at the issuing bank's request.
- Confirming bank: a bank that adds its own promise to pay on top of the issuing bank's.
A nominated bank is the one where the credit can be used, often the same bank that advised it. The seller usually presents documents there rather than sending them abroad.
The Letter of Credit Process in Seven Stages
The whole letter of credit process fits into seven stages, and each one has its own owner and its own risk:
- The buyer and seller agree a sales contract that names a letter of credit as the payment method.
- The buyer applies, and the buyer's bank opens the credit.
- A bank in the seller's country advises the credit and, if asked, confirms it.
- The seller checks every condition and asks for amendments.
- The goods are loaded and the carrier issues the bill of lading.
- The seller presents the documents and the banks examine them.
- The bank pays, and the buyer receives the documents to claim the cargo.
Stage 1: The contract sets the terms
According to the US International Trade Administration's export guide, the buyer decides which documents the credit will require. The seller should agree those documents in the contract, before any bank is involved, because changing them later costs time and fees.
The same guide advises writing payment terms that cannot be misread, such as "30 days from acceptance" rather than "net 30 days", and naming the currency in the amount itself. The Incoterm matters too. It decides who books freight and insurance, and therefore which transport and insurance documents the seller must produce. If that split is unclear, our guide to Incoterms for importers sets out who pays for what under each rule.
Stage 2: The buyer's bank opens the credit
The buyer applies to its bank, which issues the credit with every instruction about the shipment. The credit has to state an expiry date for presentation, and it has to say how it is paid: by sight payment, deferred payment, acceptance or negotiation.
Banks charge for this, mainly as a percentage of the amount. A Columbia Law study of 500 letter of credit files estimated total bank fees at about a quarter of one percent of the credit amount. Your own bank's tariff is the number to plan with, since pricing differs by bank and by country risk.
Stage 3: Advising and confirming the credit
The issuing bank sends the credit to a bank in the seller's country. If the credit is only advised, the seller still relies on the issuing bank alone to pay. If it is confirmed, a second bank adds its own undertaking, and that bank is bound from the moment it adds the confirmation.
Confirmation matters most when the seller is unsure of the issuing bank or of the country it sits in. The seller can name a preferred confirming bank, or the issuing bank picks one of its correspondents. Some sellers arrange a silent confirmation privately with their own bank, without the issuing bank's request; that arrangement sits outside UCP 600.
Stage 4: The seller reads every condition
This is the cheapest stage to fix a problem. The trade.gov guide tells exporters to review every condition, confirm with the freight forwarder that the shipping date can be met, and ask the buyer for an amendment at once if anything is impossible, wrong or even misspelled.
An amendment needs the agreement of the issuing bank, any confirming bank and the seller. Banks pay only the amount stated in the credit, even if freight or insurance ends up costing more than quoted, so the amount needs a margin before shipment, not after. Asking for partial shipments and transshipment to be allowed avoids last-minute trouble when space on a vessel changes.
Shipment, the Bill of Lading and the Clock
Stage 5: Loading and the on board notation
Once the goods are loaded, the forwarder completes the paperwork and the carrier issues the bill of lading. Under UCP 600 article 20, that bill must show the goods shipped on board a named vessel at the port of loading stated in the credit. If it carries an on board notation, the date in that notation counts as the shipment date. If it names only an "intended vessel", the notation must also give the name of the actual ship.
Containers get one useful exception: a bill of lading that shows transshipment is still acceptable, even if the credit prohibits transshipment, when the cargo travels in a container and one bill covers the whole voyage. Our explainer on the bill of lading covers its other roles as receipt and title document.
The named vessel is also what lets the buyer follow the cargo. With the ship's name or IMO number from the bill, Primo Nautic shows the vessel's live position and two arrival estimates, the ETA the captain reports and one calculated from the route, so the buyer can see whether the ship will reach port before the documents reach the buyer's bank.
Stage 6: Presentation and examination
Shipment starts a clock. Unless the credit says otherwise, original transport documents must be presented no later than 21 calendar days after the date of shipment, and never after the credit expires.
Each bank that examines the documents has a maximum of five banking days after the day of presentation to decide whether they comply. The data do not have to be identical across documents, but they must not conflict with each other or with the credit. If a bank refuses, it must send a single notice listing every discrepancy it relies on, so a seller is not hit with new objections one at a time.
Stage 7: Payment and release of documents
If the documents comply, the issuing or confirming bank must pay. Under a sight credit that happens on presentation; under a deferred payment or acceptance credit it happens at a fixed later date. The documents then travel to the buyer's bank and on to the buyer, who uses the bill of lading to claim the goods from the carrier.
Why Most Letter of Credit Documents Fail
The weakest point of the system is paperwork. An ICC Banking Commission technical briefing from 2022 estimates that 65% to 80% of documents presented under documentary credits worldwide are refused on first presentation. The Columbia study found the same pattern in its sample: only 135 of 500 files, 27%, complied the first time.
The ICC briefing traces the problems to four causes:
- Poorly drafted credits.
- Outdated or unsuitable application forms.
- A weak grasp of documentary credit workflows and of UCP 600 itself.
- Too little attention to detail while producing, shipping and collating the documents.
A discrepancy is expensive. Once documents are discrepant, neither the issuing bank nor a confirming bank is bound to pay; the seller depends on the buyer agreeing to waive the discrepancy. The briefing also lists the knock-on costs: extra bank fees for reprocessing, financing that is delayed, and documents that reach the buyer late. If the issuing bank intends to deduct a discrepancy fee, the ICC position is that the credit should say so and state the fee.
Late shipment and late presentation
Timing errors are among the most common discrepancies: a shipment after the latest date in the credit, or documents presented after 21 days or after expiry. Where a credit allows shipment in instalments, missing one instalment period ends the credit for that instalment and every one after it. Building the shipment plan around the credit's dates, not the other way round, prevents most of these.
Types of Letter of Credit You Will Meet
The type is set when the credit is opened, so both sides should agree it in the contract.
| Type | What it means | Typical use |
|---|---|---|
| Irrevocable | Cannot be changed or cancelled without the parties' agreement | Every credit under UCP 600 |
| Confirmed | A second bank also promises to pay | Buyer in a higher risk country |
| Sight | Paid when complying documents are presented | Seller wants cash on shipment |
| Deferred payment | Paid at a set date after presentation | Buyer needs time to sell the goods |
| Transferable | First seller can pass the credit to a supplier | Traders and middlemen |
| Standby | Pays only if the buyer fails to pay or perform | Guarantee behind open account trade |
A transferable credit puts the transfer charges on the first beneficiary. Standby credits, which work as a guarantee rather than a payment method, can run under UCP 600, the URDG 758 rules or ISP98, a set of rules introduced in 1998 because much of the UCP did not fit standbys. Revocable credits still exist in theory, and the trade.gov guide calls them inadvisable for exporters.
Complete Workflow at a Glance
| Stage | Who acts | Rule or deadline to watch |
|---|---|---|
| Contract | Buyer and seller | Documents, Incoterm and payment terms agreed |
| Issuance | Issuing bank | Expiry date and payment method stated |
| Advice and confirmation | Advising or confirming bank | Confirming bank bound once it confirms |
| Review | Seller | Amendments need all parties' agreement |
| Shipment | Seller, forwarder, carrier | On board notation dates the shipment |
| Presentation | Seller and banks | 21 days after shipment, five banking days to examine |
| Payment | Issuing or confirming bank | Sight or deferred, documents released to buyer |
A Worked Example: One Container, One Credit
Picture a European importer buying machine parts from a supplier in South Korea, shipped in one 40-foot container on CIF terms. The contract names an irrevocable sight credit, confirmed by a bank in Seoul, with a latest shipment date and an expiry date three weeks after it.
The supplier reads the credit and spots a misspelled company name in the consignee field. It asks for an amendment straight away, and the buyer's bank issues it within days. The container is loaded, the carrier issues a bill of lading with an on board notation naming the actual vessel, and the supplier's bank receives the invoice, packing list, insurance certificate and bill of lading well inside 21 days. The confirming bank examines them, finds them complying and pays.
On the buyer's side, the bill of lading names the ship. The importer adds it to Primo Nautic under the Cargo Shipment purpose, which gives precise, logistics-focused updates and a notification if the vessel runs late. When the ship falls behind schedule, the buyer sees the new arrival estimate early and plans customs clearance around it, while the documents travel through the banks on their own timetable.
Conclusion
A letter of credit replaces trust between buyer and seller with a bank's promise, and that promise is only as good as the documents behind it. The credit is irrevocable under UCP 600, the bank checks paper rather than cargo, and the seller has 21 days after shipment, at most, to present documents that do not conflict with each other or with the credit.
Most of the risk sits in the first and fourth stages. Agree the documents and payment terms in the contract, read every condition the moment the credit arrives, and fix errors by amendment before the goods are loaded. With 65% to 80% of first presentations refused worldwide, the sellers who get paid on time are the ones who treat the credit as a checklist from day one.